Guide
Home Loan to Build on Your Plot: Documents, Naksha and Stages
Banks ask for land papers, an approved or working naksha and a construction estimate, then release a home construction loan in stages as the house goes up.
By the Design SQR team · 27 Oct 2026 · 7 min read
To take a home loan for building a house on your own plot, banks usually ask for three things besides your KYC and income papers: the land papers that show the plot is yours, an approved (or working) building plan, and a cost estimate for the construction. The loan is then released in stages as the house goes up, after the bank's legal and technical checks and once your own share is paid. Checklists differ by bank and city, so ask your branch for its list before the drawings are finalised.
Seedhi baat: plot ke kaagaz, naksha aur estimate taiyaar ho, tabhi bank construction loan deta hai, aur paisa ek saath nahi, kaam ke stage ke hisaab se aata hai.
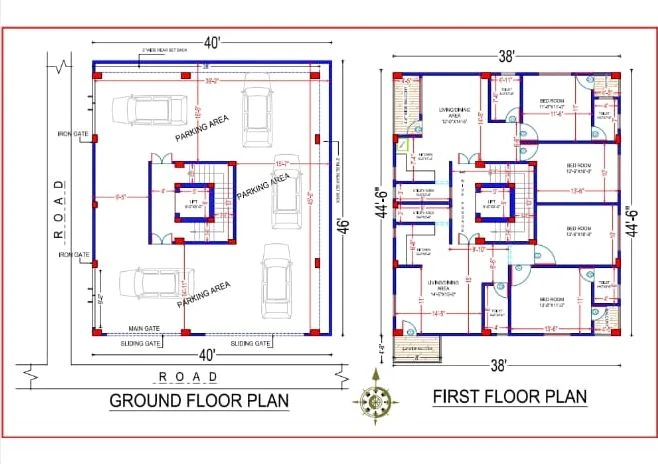
The picture above is a set of our working drawings for a 40 × 46 ft north-facing plot in Bengaluru: stilt parking for five cars around a central staircase and lift, with the living floor above. Drawings like this, with every size written on them, are what a bank's engineer reads.
Which loan fits your case
- Plot plus construction: you are buying the plot and building on it, and the bank looks at both together.
- Self-construction: the plot is already yours and you need money to build.
- Extension or improvement: you are adding a floor or rooms to a house you own.
The names vary from bank to bank, but the papers they ask for overlap a lot.
The documents banks ask for
What follows comes from two banks' own pages: HDFC Bank's property checklist for its Lucknow region, and Bank of Baroda's guides to home loan documents. Your bank's list may be longer.
Land papers
For a self-construction loan, HDFC's Lucknow checklist asks for a title search report with the title chain, made through an advocate on the bank's panel, with the khatauni showing the mutation entry and a 12-year encumbrance certificate. For a plot-plus-construction loan it also asks for the sale agreement, copies of the earlier chain of property documents, and bank proof that you have paid your own contribution.
Check your khasra and khatauni yourself before you go to the bank. Our guide to official land record sites by state lists where to look, and the Hindi version, bhulekh, khasra, khatauni kaise dekhe, walks through the steps. If the mutation after your purchase is still pending, get it done first, because the checklist asks for the khatauni that shows it.
The naksha (building plan)
- For self-construction, HDFC's checklist asks for an "Architect Approved / working map for the layout" and an indemnity bond for map approval in the bank's format. For plot plus construction, it asks for an "Architect Actual / working Map for construction".
- Bank of Baroda's guide says that for a construction loan "you must also provide a document on estimating the costs associated with property construction, approved map etc."
HDFC's list names a working map and an indemnity bond for map approval beside the approved map, so ask your branch which it will accept at sanction and which it needs before the first disbursement.
Map approval itself depends on your state. In a development authority area of Uttar Pradesh, a house plot of up to 100 sq m needs no permission, only an online registration with a self-certified plan. The system then generates a certificate of acceptance that, in the words of the 2025 bye-laws, "shall serve as a certification from the Authority" (§2.1.2). Larger plots go through approval. The steps are in naksha pass kaise karaye and the UP map approval guide.
The construction estimate
HDFC asks for an architect's cost estimate for the construction; Bank of Baroda's list names "a detailed estimate of construction costs". The bank's engineer uses it to judge what the house will cost and how the money should be released. A good estimate:
- matches the drawings, floor by floor
- lists the quantities of the main items: concrete, steel, brickwork, plaster, flooring, electrical and plumbing
- splits the cost by stage, so each disbursement can be matched to the work done
Our cost calculator gives a range for budgeting, which is not what a bank wants. For the loan file, our BOQ and cost estimation service gives item-wise quantities and a stage-wise cost split for planning payments and a home loan. Ask your bank whose signature it needs on the estimate and the map; HDFC's checklist says architect.
Your own papers
KYC, income proof and bank statements, as for any home loan. Every bank publishes its own list and changes it from time to time, so we do not repeat one here.
How the money is released: stage by stage
HDFC explains that the loan "will be disbursed either in stages or in full depending on the stage of completion of construction". Before any money is released, the property must be technically appraised, the legal documentation completed, and your own contribution invested in full. Bank of Baroda notes that a surveyor appointed by the bank visits the site.
For a house you are building, that means:
- Your share goes in first. Keep your own money ready for the early stages, because the bank's part comes after your contribution is paid.
- Each instalment follows the work. HDFC says the lender considers "only the construction stage", not a builder's instalment timeline.
- Interest can start before the EMI. With a partial disbursement you may pay "pre-EMI" interest until the full loan is disbursed, after which the EMI starts.
- Build what was drawn. Disbursement is subject to the bank's legal and technical clearance, so keep the house to the drawings you gave the bank, and tell the bank before you change the area or the number of floors.
The usual stages are foundation, plinth, each slab, brickwork, plaster and finishing. Our post on house construction stages in India explains what happens in each and what to check. Stage photos help when the bank's engineer visits.
When we build, our own payments are also linked to finished stages (booking, foundation, structure, brickwork, finishing and handover), never to dates alone, and you see every stage with photos in the client portal.
The order of work
- Check the land papers and get the mutation done.
- Get the naksha drawn and, where needed, approved. Our 2D floor plans are ready in 2–3 days, and the structural, electrical and plumbing drawings in 5 working days, with two rounds of changes after the first draft.
- Get the estimate made from those drawings.
- Apply for the loan with the full set, and ask the bank for its disbursement schedule in writing.
- Start work after sanction, with your own share ready for the first stages.
Seedhi baat: loan ki file naksha aur estimate ke baad banaiye, pehle nahi.
Common questions
Can I get a home loan to build without an approved map?
Banks list an approved map or a working map; HDFC's Lucknow checklist pairs the working map with an indemnity bond for map approval. What your branch accepts, and by which stage, is its decision, so ask before you apply.
Does the bank pay the whole loan at once?
For construction, usually not. The loan is released in stages as the work is completed, after the bank's legal and technical clearance.
What interest rate will I get?
Rates change often and depend on the bank and on you, so check the bank's own site on the day you apply. We do not list them.
Plot par ghar banane ke liye loan kaise milega?
Plot ke kaagaz (khatauni mein aapka naam), naksha aur kharche ka estimate lekar bank jaiye. Bank pehle kaagaz aur site jaanchta hai, phir kaam ke stage ke hisaab se paisa deta hai.
Sources
- HDFC Bank, checklist of property documents for home loan disbursement, Lucknow region (self-construction and plot-plus-construction loans) — https://homeloans.hdfc.bank.in/content/dam/housingdevelopmentfinancecorp/hdfc-ltd-merger/region-pdf/north-region/lucknow.pdf
- HDFC Bank, the disbursement process of your home loan — https://homeloans.hdfc.bank.in/blog/home-finance/disbursement-home-loan
- Bank of Baroda, documents required for a home loan (2 January 2023) — https://bankofbaroda.bank.in/banking-mantra/loans-borrowings/articles/documents-required-for-home-loan
- Bank of Baroda, steps to apply for a home loan — https://bankofbaroda.bank.in/banking-mantra/loans-borrowings/articles/7-step-guide-to-applying-for-a-home-loan
- Uttar Pradesh Model Building Construction and Development Byelaws 2025, §2.1.2 — http://gdaghaziabad.in/wp-content/uploads/2026/02/UP-Model-Building-Bylaws-2025_3July_250704_125142-1.pdf
Send your plot size and city on WhatsApp, or use the quote form, and we will prepare the drawings and the estimate for your loan file.
Planning a home on your own plot?
Share your plot size, facing and city. A designer will call you back within one working day with layout options and an honest cost range.